
Pays Less Taxes How to pay less tax legally as a business owner
Owners who pay less tax mostly use a handful of ordinary, legal moves: the right tax setup, a retirement plan, the deductions they qualify for, and good timing. Below is each one, who it fits, and an example with numbers.
Steven Palmieri is a Tax CFO, also called the Entrepreneur's CFO. On a free 30-minute call, we look at your last return and show you which of these fit you, and about what each one is worth.
Book a free call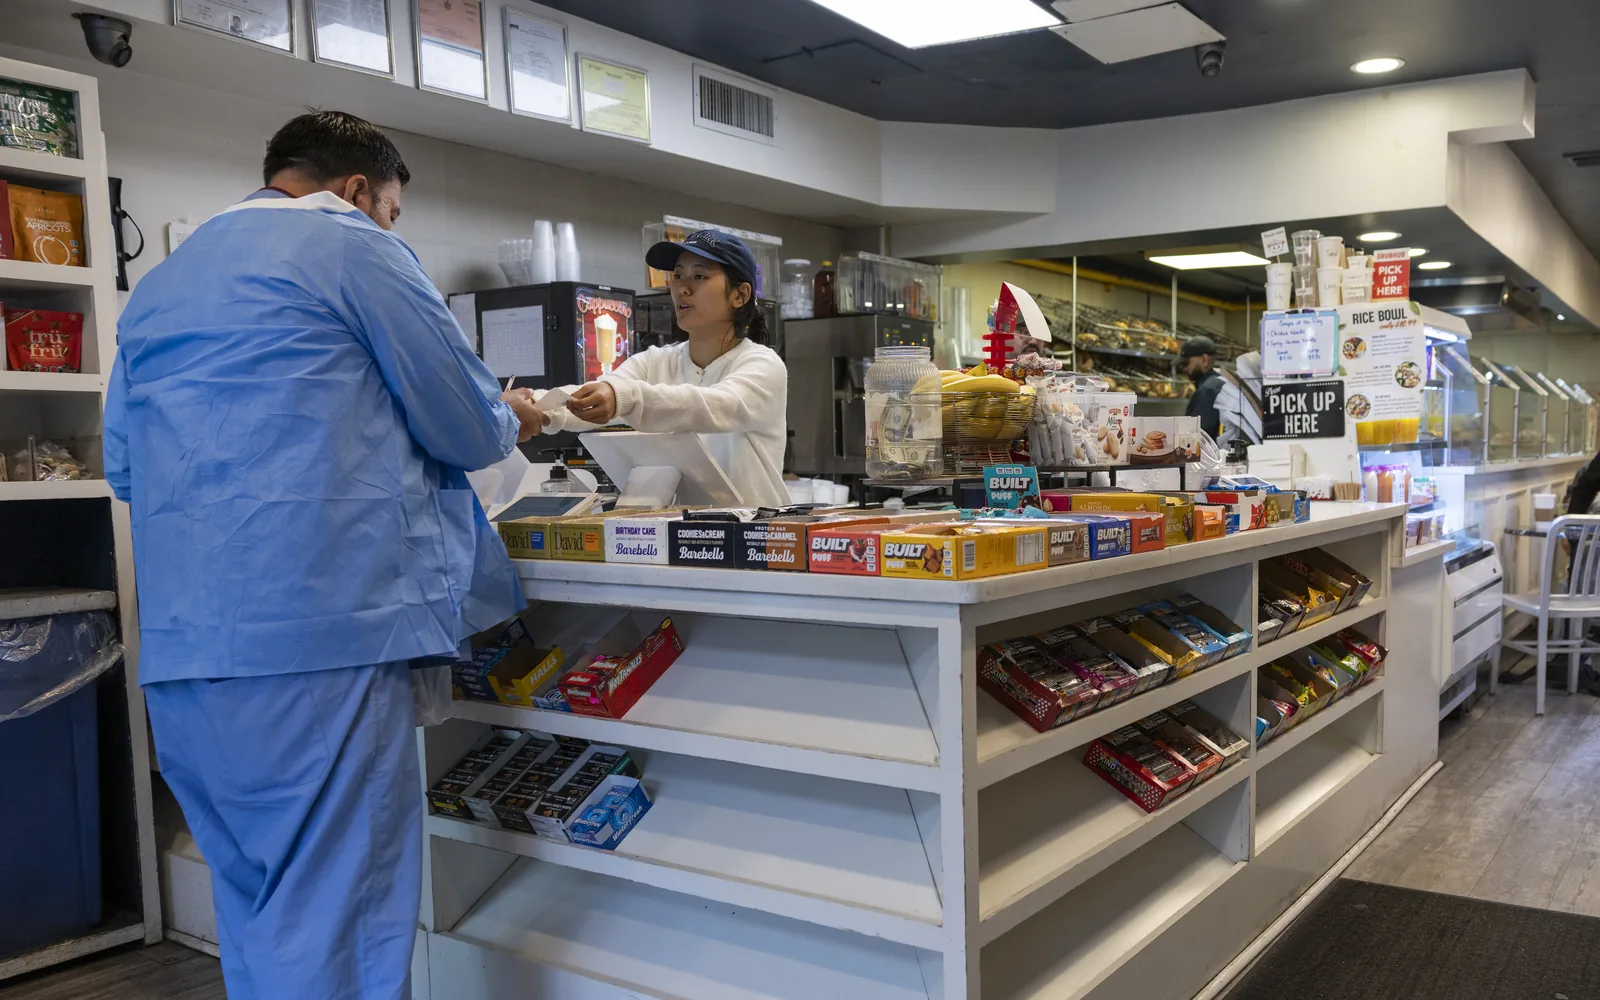
A receipt changing hands at a shop counter. Photograph by Tessa Bury, CC BY 4.0, via Wikimedia Commons.
Find the ways that fit you.

You will be talking to the Steven Palmieri practice.
The Tax CFO way
We start with last year's return and find the moves you haven't used yet. We put a rough dollar figure on each one. Then we help you set them up while the year is still open, so they show up on this year's return.
Six signs you may be paying more tax than you need to
Tap a card to see the legal move that usually fixes it.
1You pay self-employment tax on all of your profit
An S corp salary may lower it
A sole owner pays 15.3% self-employment tax on most of the profit. With an S corp, payroll tax applies to your salary, and profit above a fair salary can come out as a distribution without Social Security or Medicare tax.
2Nothing goes into a retirement plan
A Solo 401(k) or SEP IRA can cut this year's tax
Money you put into a traditional plan comes off this year's taxable income. For 2026 a Solo 401(k) can take up to $72,000, counting both the part you defer and the part the business adds.
3Your health plan has a high deductible
A health savings account adds a deduction
If your plan qualifies, you can put up to $4,400 for yourself, or $8,750 for a family, into an HSA for 2026 and deduct it. Medical bills paid from it later are tax-free.
4You bought equipment and spread the cost over years
Section 179 or bonus depreciation can deduct it this year
Equipment you buy and start using for the business by December 31 can often be deducted in full that year, instead of a slice at a time.
5You work from home and claim no home office
A home office or an accountable plan can pay you back
A room used only and regularly for the business can be deducted. The IRS shortcut allows $5 for each square foot, capped at 300 square feet.
6Your teenager helps in the business for free
Paying your child for real work can move income to a lower bracket
Your business deducts a fair wage for real work. Your child can earn up to $16,100 in 2026 with no federal income tax, the standard deduction for a single filer.
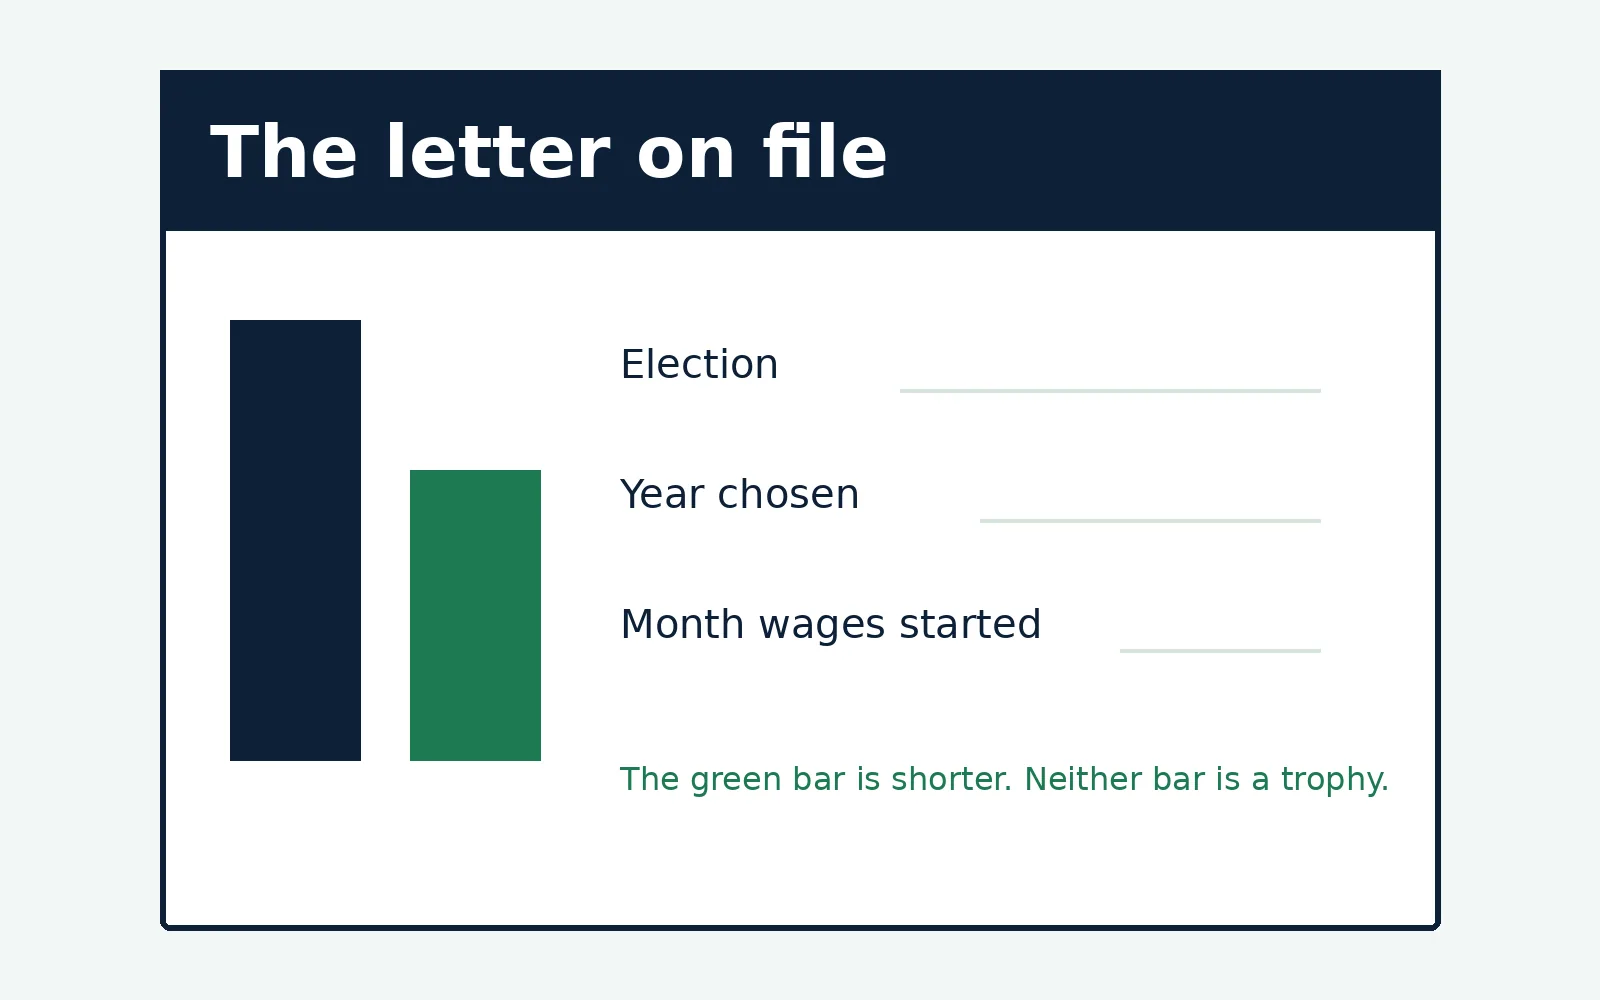
Same profit, two different tax bills.
Both bars stand for a made-up owner with $140,000 of profit. The taller bar is the federal tax when that owner files as a sole owner and does nothing else. The shorter bar is the same owner with an S corp salary, a Solo 401(k) and an HSA. In our worked example, the gap is about $15,340 of federal tax for 2026, before the cost of payroll and the extra return.
LLC, S corp or C corp.
Your tax setup decides how much of your profit carries payroll tax. Here's how each one is taxed and how to switch.
Click to compare the setups ›Tap to compare the setups ›
Your S corp salary.
Pay a fair salary through payroll and take the rest as a distribution. Here's the math, step by step.
Click to see the salary math ›Tap to see the salary math ›Timing big purchases.
Get new equipment working before December 31 and you can often write off the whole cost this year.
Click to see the timing rules ›Tap to see the timing rules ›The setup tile is a drawing made for this page. The salary tile photograph is by Paultbarham, CC BY-SA 4.0.
1. An S corp election, for owners with steady profit.
Read this part
As a sole owner or a single-member LLC, you pay self-employment tax of 15.3% on 92.35% of your profit. The Social Security part stops at $184,500 of earnings for 2026, and the 2.9% Medicare part keeps going.
With an S corp election on Form 2553, you pay yourself a fair salary through payroll. Payroll tax applies to that salary. Profit above it can come to you as a distribution, which carries no Social Security or Medicare tax.
Who it fits: owners whose profit is steady and well above what a fair salary for their work would be. It adds two costs, a payroll service and a separate business return. When the profit is small, those costs can use up most of the saving.
Example: an owner with $140,000 of profit pays about $19,780 of self-employment tax as a sole owner. As an S corp paying a $70,000 salary, the payroll tax on that salary is about $10,710. That's about $9,070 less, before the added costs. Your numbers will differ.
What keeps it legal: a salary that fits the work you do, paid through real payroll. See how to set your S corp salary.
2. A Solo 401(k) or SEP IRA, for owners who can set money aside.
Read this part
Money you put into a traditional retirement plan comes off this year's taxable income. It grows without tax each year, and you pay income tax when you take it out in retirement.
A Solo 401(k) fits an owner with no employees other than a spouse. For 2026 you can defer up to $24,500 as the employee, or $32,500 at age 50 or older. The business can add up to 25% of your pay. Both parts together top out at $72,000, not counting catch-up money.
A SEP IRA is simpler to run. The business puts in up to 25% of your pay, with a top of $72,000 for 2026. If you have employees, each eligible one gets the same percentage you do.
Example: an S corp owner paid a $70,000 salary defers $24,500 and has the company add $17,500. That's $42,000 off taxable income. In the 22% bracket, that's about $9,240 less federal income tax this year.
What keeps it legal: a plan that's open in time, and amounts inside the limits. Compare the retirement plans.
3. A health savings account, for owners on a high-deductible health plan.
Read this part
An HSA gives you a deduction now, tax-free growth, and tax-free withdrawals for medical costs. For 2026 you can put in up to $4,400 with self-only coverage or $8,750 with family coverage, plus $1,000 more at age 55 or older.
Who it fits: an owner covered by an HSA-eligible high-deductible health plan. Starting in 2026, bronze and catastrophic plans offered through a health insurance exchange also count.
Example: a family that puts in $8,750 and sits in the 22% bracket pays about $1,925 less federal income tax for the year.
What keeps it legal: an eligible health plan, deposits within the limit, and withdrawals spent on qualified medical costs, with the receipts kept.
4. The QBI deduction, for owners of pass-through businesses.
Read this part
The qualified business income deduction lets many owners of sole proprietorships, partnerships, LLCs and S corps deduct up to 20% of their business income. You don't have to spend anything to get it. You claim it on Form 8995 or 8995-A with your return.
Who it fits: most pass-through owners. Limits start once taxable income passes $201,750 for a single filer or $403,500 for a married couple filing jointly in 2026. Above those lines, the deduction depends on the wages the business pays, and many service businesses, such as consulting, law and health care, phase out of it.
Example: an owner with $80,000 of qualified business income, and taxable income under the limit, can deduct $16,000. In the 22% bracket, that's about $3,520 less tax.
What keeps it legal: it's figured from your real business income. An S corp salary doesn't count as business income, so we balance the salary and this deduction together.
5. Section 179 and bonus depreciation, for owners buying equipment anyway.
Read this part
Equipment, vehicles and machinery usually get deducted a slice at a time over several years. Section 179 and bonus depreciation pull most or all of that deduction into the first year the item is in use.
For 2026, Section 179 allows up to $2,560,000, and it starts to shrink once purchases pass $4,090,000. For property acquired after January 19, 2025, bonus depreciation lets you write off the full cost in year one.
Who it fits: an owner who already plans to buy equipment, a work vehicle, computers or furniture. The tax saving is a good reason to buy this year instead of next. It works best on things the business needs anyway.
Example: a contractor buys a $40,000 trailer and tools in November and puts them to work before December 31. Deducting the full cost this year in the 24% bracket means about $9,600 less federal income tax for this year. Later years get less depreciation, so much of the saving is about timing.
What keeps it legal: the item has to be bought and in use for the business by December 31. Read the timing rules.
6. A home office, for owners who work from a room at home.
Read this part
If you use part of your home regularly and only for the business, you can deduct it. With the IRS shortcut, you take $5 for each square foot of office, on up to 300 square feet, so $1,500 at most. The actual-cost method takes the office's percentage of your rent or mortgage interest, utility bills, renter's or homeowner's insurance and repairs.
Example: say your office is 200 square feet and the whole home is 2,000, so the office is 10%. If rent and utilities run $30,000 a year, the regular method deducts $3,000. The simple method would deduct $1,000.
Who it fits: sole owners and single-member LLCs claim it on their own return. S corp owners usually get paid back through an accountable plan instead, which is the next item.
What keeps it legal: a space used only for work, measured, with the bills kept.
7. An accountable plan, for owners who pay business costs personally.
Read this part
An accountable plan is a short written policy that lets your company pay you back for business costs you paid yourself. Common ones are the home office share, business miles in your own car and your cell phone. The company deducts the payment, and it isn't wages to you.
Who it fits: S corp and C corp owners, because they're employees of their own company.
Example: an S corp repays its owner $250 a month for a home office share and $3,000 a year for business miles. That's $6,000 a year the company deducts and the owner receives without income tax.
What keeps it legal: three IRS rules. Each repayment covers a cost the business really had. You show records, such as receipts and a mileage log, within a reasonable time. You give back any extra money.
8. Hiring your children, for owners whose kids can do real work.
Read this part
Paying your child a fair wage for real work moves income out of your tax bracket and into theirs. The business deducts the wage. Your child can earn up to $16,100 in 2026 with no federal income tax.
In a sole proprietorship, or a partnership owned only by the child's parents, wages to a child under 18 are also free of Social Security and Medicare tax. In a corporation, including an S corp, the wages carry normal payroll tax, but the income tax saving still works.
Example: a sole owner in the 24% bracket pays a 16-year-old $12,000 for filing, cleaning and social media work. The owner pays about $2,880 less federal income tax and about $1,700 less self-employment tax. The child owes no federal income tax on that pay.
What keeps it legal: real work, pay that fits the work, a timesheet, and real payroll paperwork such as a W-2.
9. Tax credits, for owners who hire, build or start a plan.
Read this part
A credit lowers your tax dollar for dollar, so it's worth more than a deduction of the same size.
- Retirement plan startup credit: a small business that starts a new plan for its employees can claim up to $5,000 a year for the first three years, depending on how many employees it has. It can claim $500 more a year for adding automatic enrollment.
- Research credit: a business that develops or improves a product, a process or software may qualify. A qualified small business can use up to $500,000 of it against its payroll tax.
- Small business health care credit: an employer with fewer than 25 full-time-equivalent employees that buys coverage through the SHOP marketplace may qualify.
Who it fits: owners with employees, owners who build or improve things, and owners starting a retirement plan. What keeps it legal: records of the work or the cost, kept as it happens.
How the ways add up for one owner.
Read this part
The moves stack. In our worked example, a made-up single owner with $140,000 of profit uses an S corp with a $70,000 salary, a Solo 401(k) and an HSA. Federal tax for 2026 drops by about $15,340, and $46,400 goes into savings accounts that belong to the owner.
The figure already counts the smaller QBI deduction that comes with a salary. It leaves out state tax and the cost of payroll and the business return. See every step of the math.
Bring your return to the call, and we'll redo this math with your figures. Some owners gain the most from an S corp. Others gain more from a retirement plan or a purchase timed before December 31.
What keeps a tax saving legal.
Read this part
Every move on this page is written into the tax law, and the IRS forms are built around them. They hold up when four things are true.
- It's a real business cost or a choice the law offers. The IRS lets a business deduct costs that are ordinary and necessary for its line of work.
- You have the records: receipts, a mileage log, timesheets, payroll reports and plan statements.
- The amounts fit the facts: a salary that fits the work, a child's wage that fits the job, a home office you measured.
- It's done on time. Most moves for this year have to be in place by December 31. A few, like a SEP IRA deposit, can wait until you file.
Questions owners ask before the call.
Read this part
Is it legal to pay less tax? Yes. Choosing your tax setup and using the deductions and credits the law offers is legal tax planning. What matters is that the facts and the records back up each one.
How much could I save? It depends on your profit, your setup and what you already use. On the free 30-minute call, we look at your last return and show you which moves fit and about what each one is worth.
Do I need to switch to an S corp? Not always. At a modest profit, the cost of payroll and a second return can eat most of the saving. We run the numbers both ways and show you.
What happens after the call? Want help with the moves? You get a short engagement letter with the work spelled out and the fee, and we begin after you sign.
Who you'll talk to.
Read this part
Steven Palmieri is a Tax CFO for business owners who want to pay less tax and keep every move on solid ground. We keep your books in QuickBooks Online, plan your taxes during the year, and prepare your return. We can meet by video, in person when it helps, or on a call with your banker.
The first call is free, takes 30 minutes, and happens by video. If you want help after it, we send a letter that lists the work and the fee.
Book a free 30-minute call